
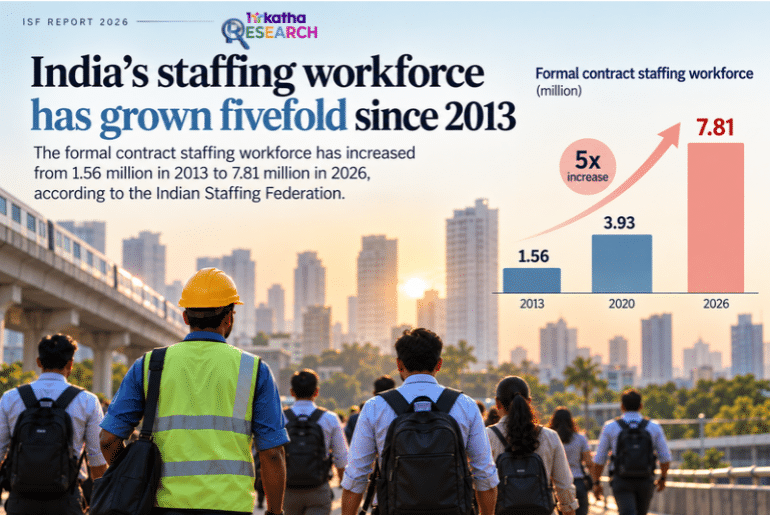
India’s contract staffing industry has grown fivefold since 2013. But the pace of that expansion is slowing, even as the industry claims a larger role in the country’s formal employment market.
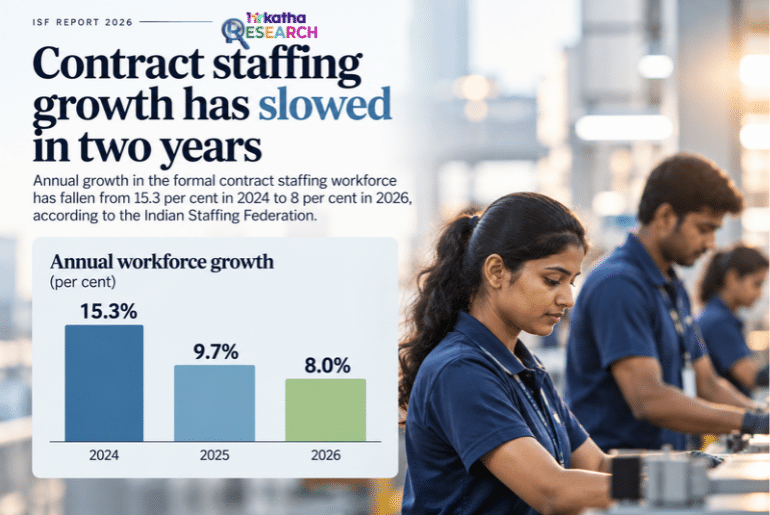
The formal contract staffing workforce reached 7.81 million in 2026, up from 1.56 million in 2013, according to the Indian Staffing Federation’s (ISF) latest quarterly report, covering April to June 2026. Annual workforce growth, however, has fallen from 15.3 per cent in 2024 to 8 per cent in 2026.
Alongside those figures sits a much larger claim. Citing EPFO payroll data, the Federation says the category labelled ‘Expert Services / Manpower Suppliers’ accounts, month after month, for 40 to 45 per cent of India’s net formal payroll additions.
The figures do not contradict each other. One measures the growth of a staffing workforce; the other describes a share of net payroll additions in an EPFO category. But placing them together raises a question the report does not answer: how much of the industry’s contribution reflects the creation of new jobs, and how much reflects the movement of existing work into formal employment?
The federation represents about 120 staffing companies, and its quarterly research draws on an email survey of member organisations. The report acknowledges that respondents answered closed-ended questions from their own experience and that the exercise was not conducted in a controlled environment. The figures describe members, as reported by members. They give a useful picture of demand among participating firms. They cannot establish, on their own, the industry’s contribution to employment across the economy.
What the 40% to 45% measures
The distinction matters because the report does not say whether the EPFO category cited by the federation is the same as the contract staffing industry.
The report gives no breakdown of the category. Elsewhere it states that manpower suppliers accounted for around half of the expert-services share of net EPFO additions in the first quarter of the previous year. If that relationship held, manpower suppliers alone would represent about one-fifth of net additions rather than two-fifths.
That is an illustration, not an estimate of the current share. The report does not establish that the same proportion continued into 2026.
There is a second limitation. EPFO payroll additions cannot, by themselves, establish how many new jobs have been created. An employee moving from a client’s payroll to a staffing company’s payroll changes the employment arrangement without creating another position.
A worker who was informal and now has EPFO coverage represents a gain in formalisation, but not an additional job in the economy.
Both developments matter. Formalisation can extend social-security coverage and bring workers into more visible employment arrangements. But its economic significance differs from the creation of work that did not exist before.
The federation’s own report credits the industry with both employment creation and formalisation. The difficulty is that the figures presented do not separate the two.
Three measures of growth, three different answers
The uncertainty extends to the industry’s reported headcount growth.
Among ISF members, whose workforce is a separate measure from the 7.81 million national figure above, the staffing workforce reached 1.95 million in the April to June quarter. The report cites annual growth of 7.5 per cent and the addition of 1.14 lakh formal jobs over 12 months.
Those figures do not match. If the workforce increased by 1.14 lakh to 1.95 million, the implied growth rate is about 6.2 per cent. Compounding the four quarterly growth rates in the report’s chart produces about 8.9 per cent. The discrepancies leave the direction of the trend intact and the size of the gain uncertain.
Quarterly growth recovered to 2.6 per cent in April to June 2026, following a 0.2 per cent fall and a 0.9 per cent rise in the two preceding quarters. Demand is improving after a weak period. Yet the longer-term industry series points to a deceleration from the double-digit growth recorded in 2022 to 2024.
The distinction between recovery and acceleration matters. A workforce can begin growing again without returning to its earlier growth trajectory.
Manufacturing is hiring. Banking is pulling back
Beneath the aggregate figures, demand differs by sector.
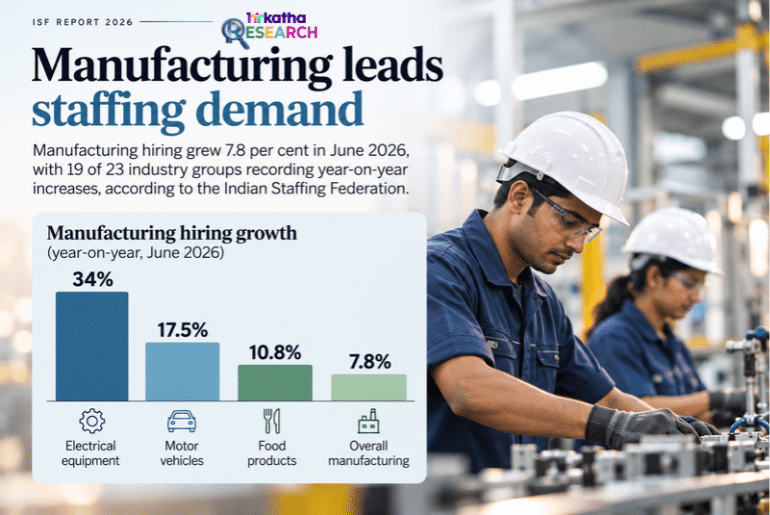
Manufacturing hiring increased 7.8 per cent in June, with 19 of 23 industry groups recording year-on-year increases. Electrical equipment led with 34 per cent growth, followed by motor vehicles at 17.5 per cent and food products at 10.8 per cent.
Consumer-facing sectors also contributed. FMCG hiring rose 7 per cent and telecom 6 per cent. Fresher hiring in retail and hospitality increased 30 per cent each in May, while retail sales roles recorded a 50 per cent rise.
Banking moved in the opposite direction. Hiring fell 15 per cent in May, while insurance hiring increased 16 per cent in June. Among fresher roles in financial services, relationship manager hiring rose 75 per cent and loan officer hiring 62 per cent. The federation points to regulatory limits on what banks can outsource.
These figures indicate where demand is strengthening and weakening, but they have an important limitation. The report provides percentage changes without disclosing the underlying hiring volumes. A 50 per cent increase in one occupation can represent fewer jobs than a modest increase in a much larger category. Without those bases, the relative importance of each hiring surge remains difficult to assess.
IT staffing’s recovery follows a steep contraction
The technology segment offers an even clearer example of why positive growth needs context.
IT staffing recorded 7 per cent year-on-year growth and 2 per cent quarterly growth in April to June 2026. The recovery followed a severe contraction in FY23, when three consecutive quarterly declines of 3.3, 6 and 11.6 per cent together reduced headcount by about one-fifth. The subsequent recovery has been gradual and uneven. The latest quarterly increase suggests stabilisation, but the longer history makes it difficult to describe the rebound as a return to sustained growth.
Within technology, demand is also shifting. AI and machine-learning roles grew 25 per cent year on year in June, even as overall IT hiring declined 3 per cent. Global capability centre hiring increased 8 per cent across major metros in May, with Chennai recording 25 per cent growth, Hyderabad 20 per cent and Pune 16 per cent.
The report reads several consecutive quarters of GCC hiring growth as a structural trend. Several quarters is a short record beside an IT staffing workforce that lost a fifth of its headcount in three.
The broader pattern is one of selective recovery. Employers are expanding recruitment in particular technical specialisations while staying cautious elsewhere.
For staffing companies, that creates opportunity. It also illustrates the industry’s exposure to changes in client demand. Flexibility for the client can mean considerable headcount volatility for the staffing provider.
Are young workers entering new jobs or formal payrolls?
The federation also presents staffing as an important entry route into formal employment for young workers.
It notes that 57 to 61 per cent of new EPFO subscribers are aged 18 to 25. But that figure describes new subscribers across EPFO, not employees recruited through staffing companies.
The report does not establish how many staffing hires are entering employment for the first time, how many had worked informally or how many move on to permanent positions with client organisations. Those distinctions would help determine whether staffing is creating new entry-level opportunities, formalising existing employment or providing a temporary route between different employment arrangements.
The federation also cites Rs 57,509 crore in social-security and GST contributions for 2024-25. The figure combines social-security contributions with tax receipts and does not split the two, so it cannot be read as the amount contributed towards workers’ social security.
The difference between creating jobs and formalising work
None of these qualifications diminishes the importance of formal staffing.
For workers who lacked documented employment or social-security coverage, formalisation is a real improvement. For employers, staffing arrangements can help manage fluctuations in demand. And for an economy with a substantial informal workforce, the expansion of formal payroll coverage is significant in its own right.
But employment creation and formalisation are different outcomes, and they should not be counted as though they were interchangeable.
The ISF report provides evidence of an industry that has expanded considerably over the past decade, is now growing more slowly and faces sharply different hiring conditions across sectors. It also points to a substantial role for expert services and manpower suppliers in formal payroll additions.
What it does not establish is how many of those additions represent jobs that would not otherwise have existed. That distinction matters because formalisation and employment creation, while both valuable, measure different kinds of progress.
A worker appearing on a formal payroll is an important outcome. Whether that worker fills a job that did not exist before is a different question.